Money Checklist by Age: Smart Moves From 20s to 60s
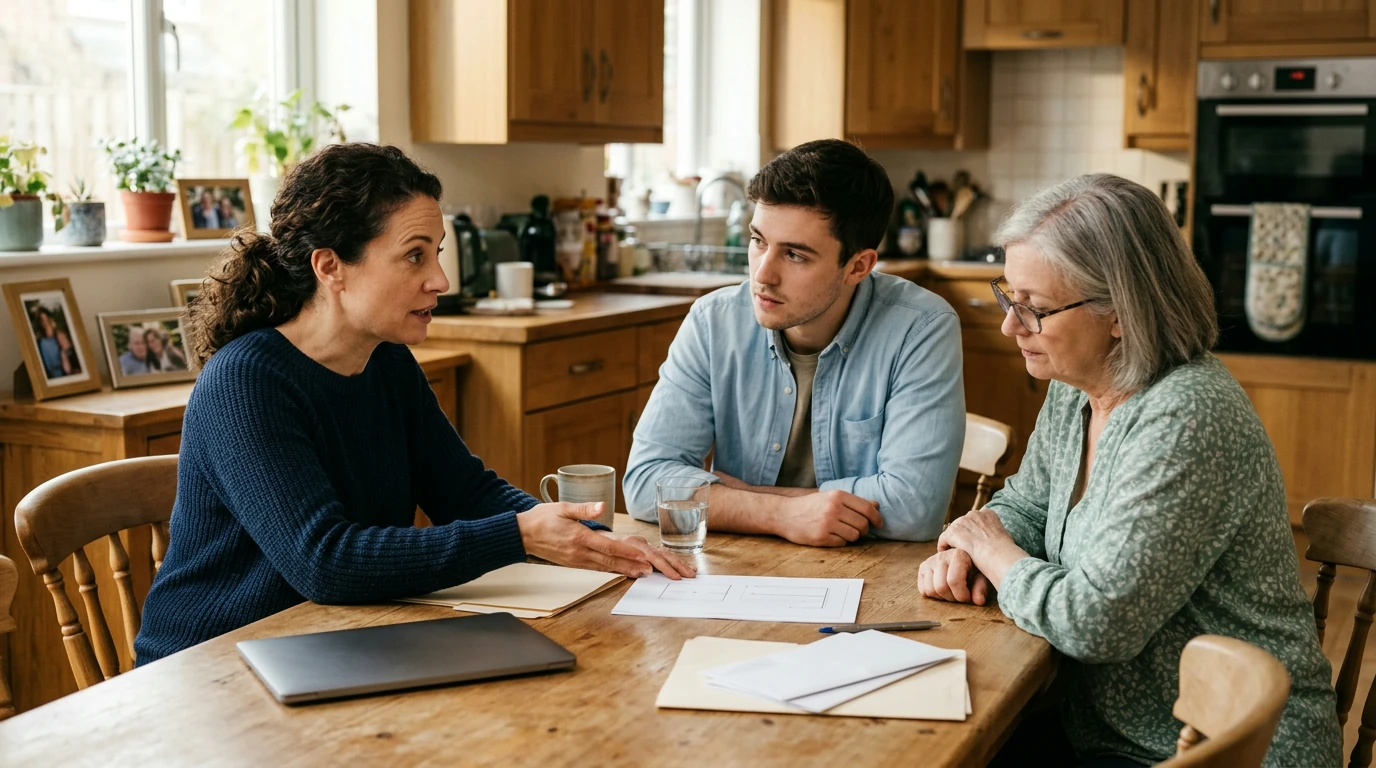
Financial Planning Checklist by Age: Smart Money Moves for Every Decade
A clear plan makes money decisions easier—especially when priorities change over time. Use this age-based checklist to set strong foundations in your 20s, build momentum in your 30s, protect your progress in your 40s and 50s, and prepare for a confident retirement.
Start with the essentials that apply at every age
Some money moves are evergreen. When these basics are solid, the decade-specific steps become far easier to execute.
- Track monthly cash flow: income, fixed bills, flexible spending, and irregular expenses.
- Build an emergency fund: start small, then work toward 3–6 months of core expenses.
- Pay down high-interest debt first: avoid revolving balances when possible.
- Automate saving and investing: set it once and let progress happen in the background.
- Protect the basics: health coverage, disability protection through work if available, and appropriate deductibles.
- Review beneficiaries on retirement accounts and insurance after major life changes.
- Check credit reports for accuracy and keep utilization low to protect scores.
Age-based financial planning checklist at a glance
| Age range | Primary goals | Top actions this year |
|---|---|---|
| 20s | Foundation | Build savings habit, eliminate toxic debt, start retirement contributions |
| 30s | Growth | Increase savings rate, buy adequate insurance, plan for home/family costs |
| 40s | Acceleration | Maximize retirement, optimize taxes, shore up protection and estate basics |
| 50s | Pre-retirement | Catch-up contributions, refine retirement budget, plan healthcare strategy |
| 60s+ | Distribution | Claim Social Security strategically, manage withdrawals, update legacy plan |
In your 20s: build the foundation
Your biggest advantage is time. The goal is to set up simple systems that make “good with money” your default.
- Create a simple spending plan and target a savings rate that can grow over time.
- Build a starter emergency fund (often one month of expenses), then expand it.
- Tackle high-interest debt aggressively; the avalanche method (highest APR first) can reduce interest fastest.
- Begin retirement investing early—even small contributions can compound meaningfully.
- Set up a basic financial “file”: logins list, account list, and annual review reminders.
- Start credit building with on-time payments and low utilization; avoid unnecessary new accounts.
- Learn investing fundamentals: diversification, fees, and a long-term time horizon.
For budgeting templates and cash-flow structure, the Consumer Financial Protection Bureau (CFPB) budgeting resources are a reliable place to start.
In your 30s: grow net worth while juggling bigger goals
This decade often brings higher income—and higher commitments. The win is to increase savings while building protection for the people and assets that now depend on you.
- Increase retirement contributions after raises; stepping up 1–2% at a time is a practical approach.
- If buying a home, budget beyond the mortgage: maintenance, insurance, taxes, repairs, and furnishings.
- Plan for family-related costs (childcare, education savings, dependent care benefits).
- Review insurance needs: term life (if others rely on your income) and adequate liability coverage.
- Build a sinking fund for planned big expenses (car replacement, travel, home projects).
- Prioritize tax-advantaged accounts when eligible (workplace plans, IRAs, HSAs where available).
- Update beneficiaries and create basic estate documents (will, healthcare directives) when life changes.
Keep an eye on current limits and rules for retirement accounts via the IRS retirement plans resource.
In your 40s: accelerate retirement and reduce risk
Your earnings power may be strong, but time to retirement is no longer “forever.” This is where clearer targets and fewer leaks can create outsized progress.
- Stress-test retirement progress: compare your current savings pace to your target retirement age.
- Identify “leakage” in spending and redirect it to retirement, brokerage investing, or debt payoff.
- Review asset allocation and risk level to ensure it still matches goals and time horizon.
- Evaluate college funding decisions against retirement security; avoid sacrificing core retirement goals.
- Strengthen protection: disability coverage, umbrella liability (if warranted), and updated life coverage.
- Do a deeper tax check: withholding accuracy, capital gains planning, and traditional vs. Roth mix.
- Document key plans: account access, password manager, and a family emergency checklist.
In your 50s: turn plans into a retirement-ready strategy
Now it’s less about “someday” and more about turning goals into a timeline. Clarity around spending and healthcare can prevent expensive surprises later.
In your 60s and beyond: manage withdrawals and protect independence
For benefit basics and timing considerations, confirm details with the Social Security Administration.
A simple annual routine to stay on track (any age)
Printable checklist to make each step easier
Recommended downloads:
Financial Planning Checklist by Age – Your Ultimate Guide to Smart Financial Decisions,
TikTok Sprint Blueprint: Your 7-Step Weekly Content Checklist (+ Bonus Gift!),
Preventing and Relieving Screen-Induced Eye Strain – Practical eBook Guide.
FAQ
How much should be saved for retirement by each age?
A common rule of thumb is to aim for rough income multiples over time (often around 1x by 30, 3x by 40, 6x by 50), but the right target depends on your savings rate, retirement age, lifestyle goals, and when you started. Focus on consistent contributions and gradually increasing your rate as income grows.
What comes first: paying off debt or building an emergency fund?
Build a small starter emergency fund first so surprise expenses don’t push you further into debt, then prioritize high-interest balances while continuing to grow your fund. Exceptions can include very high APR debt or situations where income is unstable and a larger cash buffer is urgently needed.
When should Social Security be claimed?
Claiming earlier typically means a smaller monthly benefit, while waiting (up to age 70) generally increases the monthly amount. The best choice depends on health and longevity expectations, whether you’re still working, and how benefits fit into a household plan with a spouse.




Leave a comment