A Payday-Proof Budget That Works in Real Life
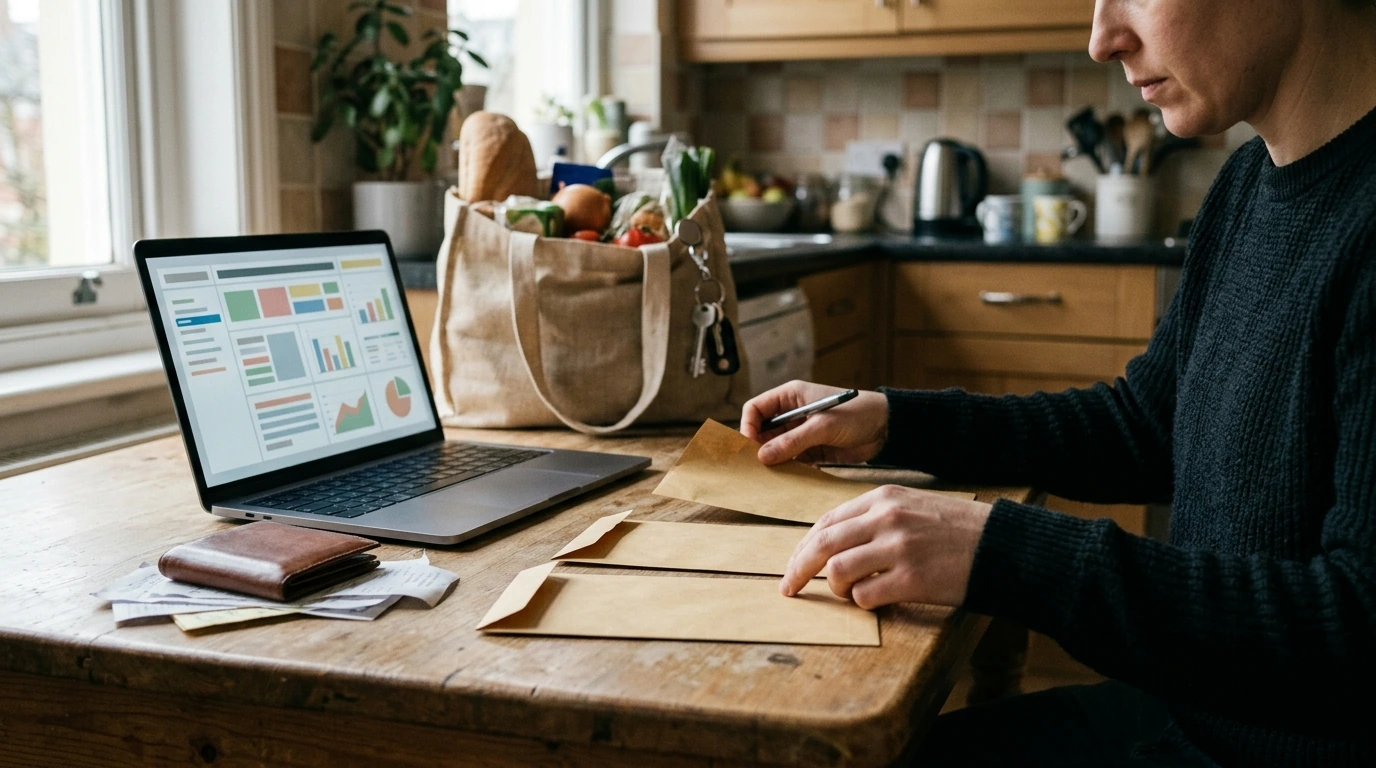
Budget Without the B.S.: A Real-World Budget That Holds Up on Payday (and on Random Tuesdays)
Budgets fail when they’re built for a perfect month that never happens. Our team built this no-fluff approach for real life: irregular expenses, impulse traps, and the “oh right, that bill exists” moments—without making you feel like you’re on financial punishment. The goal is simple: a budget that’s easy enough to use, flexible enough to survive, and clear enough to show what’s actually possible with your money.
What a “realistic budget” actually does (and what it stops doing)
A realistic budget stops pretending every month is identical and plans for the messy parts on purpose. Instead of forcing perfection, it gives every dollar a job while letting progress count even when you don’t nail it every week. You separate fixed bills, flexible spending, and irregular expenses so nothing has to “come out of nowhere.”
Most importantly, you keep categories few and behavior-based (not aspirational). Then you add simple rules for decision-making: what happens when groceries jump, your hours dip, or a goal changes mid-month. That’s what keeps your plan from collapsing into a restart cycle.
The fast start: get numbers that aren’t fantasy
Start with take-home income—what actually hits your account. If your income changes month to month, use a conservative baseline (your lowest typical month) and treat anything above that as “bonus money” with a pre-decided purpose.
Next, list non-negotiables: housing, utilities, minimum debt payments, insurance, transportation basics, phone, childcare—only what truly must be paid. Then pull your last 30–90 days of transactions and highlight repeat offenders: takeout, subscriptions, delivery fees, convenience buys, and the “small” purchases that stack.
Finally, add irregular-but-inevitable costs: annual renewals, car repairs, medical co-pays, gifts, school fees, pet care, holidays, and travel. Pick one primary money goal for the next 30 days (not ten)—like getting current, building a starter buffer, or stopping overdrafts.
The three-bucket framework that keeps the budget from collapsing
Most budgets “break” because irregular costs weren’t included or because flexible spending got funded first. The three-bucket framework keeps you steady:
- Bucket 1 — Bills & essentials: must-pay items that protect housing, health, work, and stability.
- Bucket 2 — True expenses: irregular costs turned into small monthly amounts so the money is waiting when the bill arrives.
- Bucket 3 — Choices: everything flexible (fun, upgrades, convenience). This is where you decide how much is safe to spend—without risking rent.
| Bucket | Category examples | How to set the amount |
|---|---|---|
| Bills & essentials | Rent/mortgage, utilities, minimum debt payments, insurance, basic groceries, transportation to work | Use actual bills + a realistic weekly grocery number based on recent spending |
| True expenses | Car maintenance, annual subscriptions, medical, gifts, back-to-school, holidays, pet care | Estimate annual/irregular total and divide by 12 (or by pay period) |
| Choices | Dining out, entertainment, shopping, extras, convenience fees, upgrades | Start with what’s left after Bucket 1 + 2, then set caps that won’t require “budget amnesia” |
Make it payday-proof: the “when money arrives” plan
A budget is only real if it works on payday. As soon as money arrives, assign it a job in this order: essentials first, true expenses second, choices last. If you’re paid biweekly, plan for two-check months and decide ahead of time what the “extra” check will do (buffer, debt, sinking funds, savings) before it shows up and disappears.
One clean rule we like for leftovers is 50% to goals (debt/savings) and 50% to lifestyle, adjusted for urgency. And if timing keeps causing late fees or overdrafts, build a starter buffer—even a small one—so the calendar stops controlling your life.
The anti-burnout method: weekly check-ins that take 10 minutes
Use our digital guides as working systems (not just reads)
If you want a ready-to-use structure, we recommend using Budget Without the B.S.: A Real-World Guide to Making a Budget That Actually Works (Digital PDF) as your monthly toolkit: set up the three buckets, list your true expenses, and build simple payday assignments you can repeat. Month one is about stability, not optimization—keep categories consistent so patterns become obvious.
If you’re a creator or side-hustler with variable income, pairing your money plan with a weekly workflow helps your budget feel less random. Our team built TikTok Sprint Blueprint: Your 7-Step Weekly Content Checklist to keep your week focused—so income swings are less chaotic and your “baseline month” becomes easier to predict.
For trustworthy budgeting basics and consumer protections, you can also reference the Consumer Financial Protection Bureau (CFPB) budgeting tools and the FDIC Money Smart program.
Common budget breakdowns (and the fixes that actually stick)
FAQ
How do digital budgeting guides work if income changes every month?
You start with a conservative baseline income (your lowest typical month), assign each paycheck to essentials first, then true expenses, then choices. When extra income comes in, you follow a pre-decided rule—like putting it toward a buffer, debt, or sinking funds—so the plan stays stable instead of reinvented every month.
What’s the difference between a “realistic budget” and tracking expenses?
Tracking shows what already happened; a realistic budget assigns money ahead of time so your bills, true expenses, and choices are planned. Weekly check-ins let you adjust before a problem snowballs, instead of discovering the damage after the month is over.
How long does it take for a budget to start feeling normal?
Expect the first 2–4 weeks to be calibration while you fix category amounts and add missing true expenses. By month two, most categories stabilize, especially if you keep weekly check-ins short and make small adjustments instead of rewriting the whole plan.





Leave a comment