Use AI to Find Hidden Fees and Lower Monthly Bills
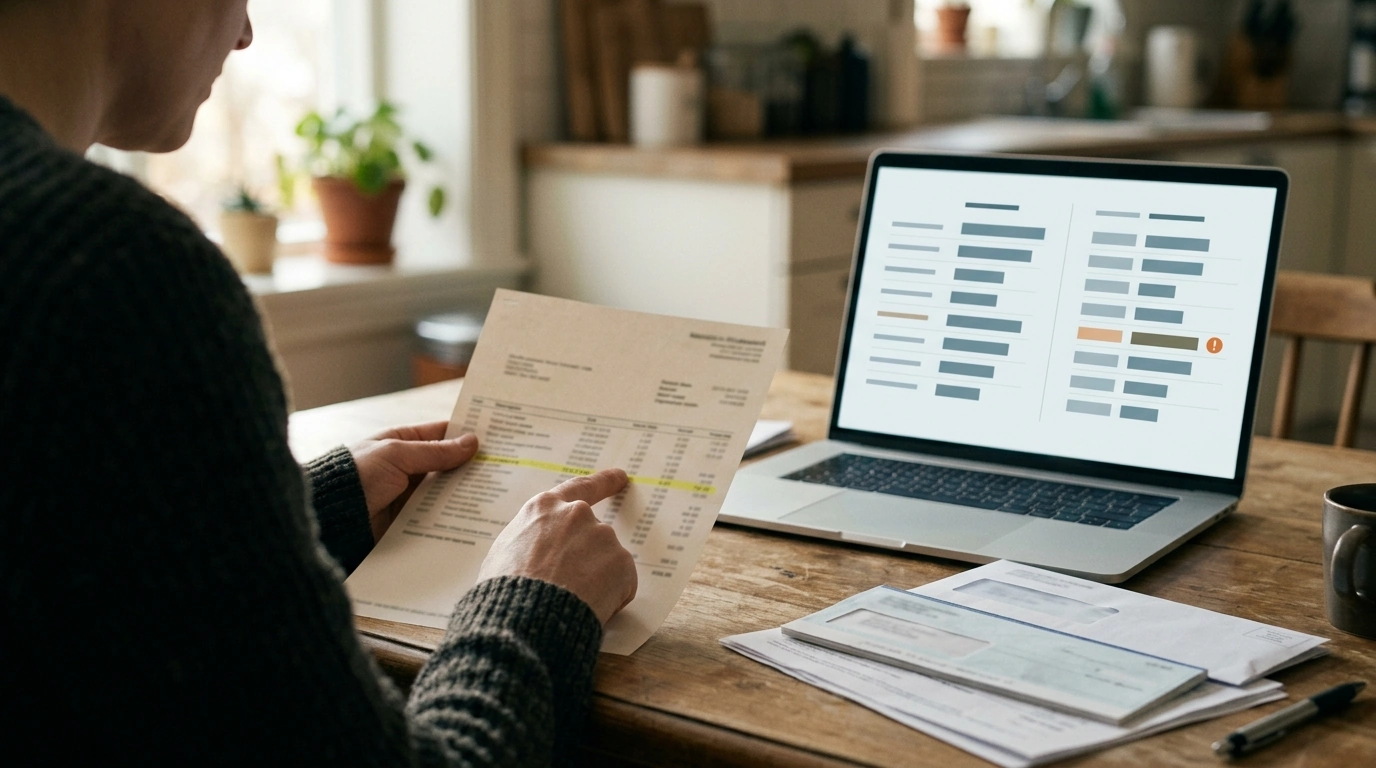
How AI Spots Hidden Fees in Your Bills and Helps You Cut Monthly Costs
Small add-on charges, “service” line items, and pricing changes can quietly inflate monthly bills. With the right approach, AI can help flag unusual patterns, compare statements over time, and surface fees worth challenging—so budgets get clearer and spending gets easier to control.
Why hidden fees are so easy to miss
Most billing statements are built to confirm what you owe—not to help you audit why the amount changed. That design makes it surprisingly easy for small charges to blend into the background.
- Statements summarize, they don’t explain. Key details may be buried in line items, footnotes, or “messages” sections that are easy to skip.
- Many fees look official. Labels like “regulatory recovery,” “convenience fee,” or “administrative charge” can appear legitimate even when the amount changes without warning.
- Auto-pay removes friction. Paperless billing and auto-pay reduce the chance you’ll notice a $2–$8 creep that persists for months.
- Bundles and promos blur the math. A discount expiring or a plan quietly migrating can look like a normal month-to-month fluctuation.
What AI can realistically do with your statements
AI works best as a “bill translator” and “change detector.” It can’t enforce a provider’s policy for you, but it can make changes obvious and document them clearly.
- Extract key fields (billing period, provider, plan name, taxes/fees, totals) from PDFs or copied text and organize them consistently.
- Detect anomalies such as brand-new fees, sudden increases, duplicate charges, and mismatches between plan terms and billed amounts (when you provide the plan details).
- Compare month-over-month patterns and highlight deviations that deserve a closer look.
- Summarize complex bills into a short list of “questions to ask” before paying.
- Create dispute-ready notes that capture what changed, when it changed, and where it appears on the statement.
Common “quiet” charges AI can flag
| Category | Examples | What to verify |
|---|---|---|
| Telecom & internet | equipment rental, modem fee, regional sports fee, “network access” | Whether the fee is optional, tied to hardware you still have, or increased after promo ended |
| Banking & cards | maintenance fee, paper statement fee, foreign transaction fee | Account terms, waiver requirements, and whether a different account tier removes it |
| Subscriptions | trial-to-paid conversion, annual renewal, add-on bundle | Cancellation policy, renewal notice, and whether multiple memberships overlap |
| Utilities | service charge changes, late fee, reconnection fee | Rate plan, billing period, payment posting date, and whether assistance programs apply |
| Insurance | policy fee, installment fee, rider/add-on | Payment frequency cost, optional riders, and whether discounts dropped |
A simple AI workflow: from bill to actionable savings
A consistent workflow matters more than fancy tools. The goal is to make each provider easy to compare over time, then focus attention on the few items that drive the biggest recurring waste.
- Collect statements. Download PDFs or take screenshots for the last 3–6 months for each provider.
- Name files consistently. Use a format like Provider_YYYY-MM so comparisons stay clean.
- Extract the essentials. Have AI pull total due, due date, plan name, line items, taxes/fees, discounts, and any one-time charges.
- Request a change log. Ask: “What’s different from last month?” and require dollar deltas for each difference.
- Prioritize the flags. Tackle recurring charges first, then “one-time” fees that show up again.
- Document precisely. Copy the exact line-item text and note the page/section where it appears—this speeds up support calls and reduces back-and-forth.
When you repeat the same steps across internet, mobile, insurance, and subscriptions, patterns become obvious—especially when a fee appears right after a promo ends or a plan “upgrade” occurs.
How to prompt AI without sharing sensitive data
You don’t need to share full statements to get useful results. Minimizing what you provide reduces risk while still enabling strong comparisons.
If you want a practical yardstick for responsible AI use, the NIST AI Risk Management Framework (AI RMF 1.0) is a solid reference for thinking about privacy and risk tradeoffs.
What to do when AI finds a questionable charge
For billing disputes related to consumer financial products, the Consumer Financial Protection Bureau (CFPB) has clear guidance on documenting issues and communicating effectively. For subscription-related traps and renewals, the Federal Trade Commission (FTC) is a helpful starting point for understanding negative option marketing.
Make savings stick with a monthly “fee audit” habit
Resources to speed up results
- How AI Finds Hidden Fees Lurking in Your Bills – Smart eBook Guide to Using ai for finding hidden fees in bills, Cut Monthly Costs, Analyze Statements, and Take Control of Your Money
- Preventing and Relieving Screen-Induced Eye Strain – Practical eBook Guide | Eye Strain from Screens What to Do | Digital Download
FAQ
Can AI really find hidden fees, or does it just summarize my bill?
AI can extract line items and compare them across months to highlight new fees, increases, and repeating “one-time” charges. You still need to verify whether a fee is valid by checking plan terms and provider policies.
What bills should be checked first to cut monthly costs faster?
Start with recurring bills that have lots of line items and frequent promotions: internet/cable, mobile plans, insurance, banking fees, subscriptions, and utilities. Month-over-month increases and recurring add-ons usually offer the quickest wins.
Is it safe to use AI with my statements?
It can be safer when you redact personal identifiers and share only the line-item text and amounts needed for analysis. Avoid uploading full statements when a minimal excerpt will do, and follow the privacy practices of the tool you use.





Leave a comment